Ask a South African what a bakkie costs and you get an instalment. “About R8,000 a month.” Nobody says R650,000, which is what R8,000 a month adds up to over six years. The dealer sells the instalment. The bank sells the term. This guide is about what the bakkie costs by the time it is yours.
The forum rule of thumb is that R500,000 of bakkie is R10,000 a month. At today’s rate it is closer to R8,400, and that sounds fine. Then the insurance, the diesel and the tracker arrive, and it is a R16,000 a month bakkie.
Every sum below is worked at the prime rate of 10.5 percent, where the Reserve Bank had it on 22 September 2026. Prime is the starting rate banks lend at. The Reserve Bank decides again on 23 September, and every figure here moves with prime. The prices are asking prices on live listings in September 2026: what sellers ask, not what bakkies sell for.
What the instalment hides
Three things sit inside every instalment: the loan, the interest and the fees. The fees are capped by the National Credit Act: an initiation fee of R1,207.50 once, and a service fee of R69 a month, VAT included. The initiation fee is usually added to the loan, so you pay interest on it too. Over six years the fees come to about R6,200.
The interest is the big one. The bank works out one payment that, made every month for the whole term, clears the loan and the interest on whatever is still owed. Early on, most of each payment is interest. The instalment does not include insurance, a tracker, diesel, the licence or servicing. Those roughly double the bill.
Example one: a used Ranger double cab
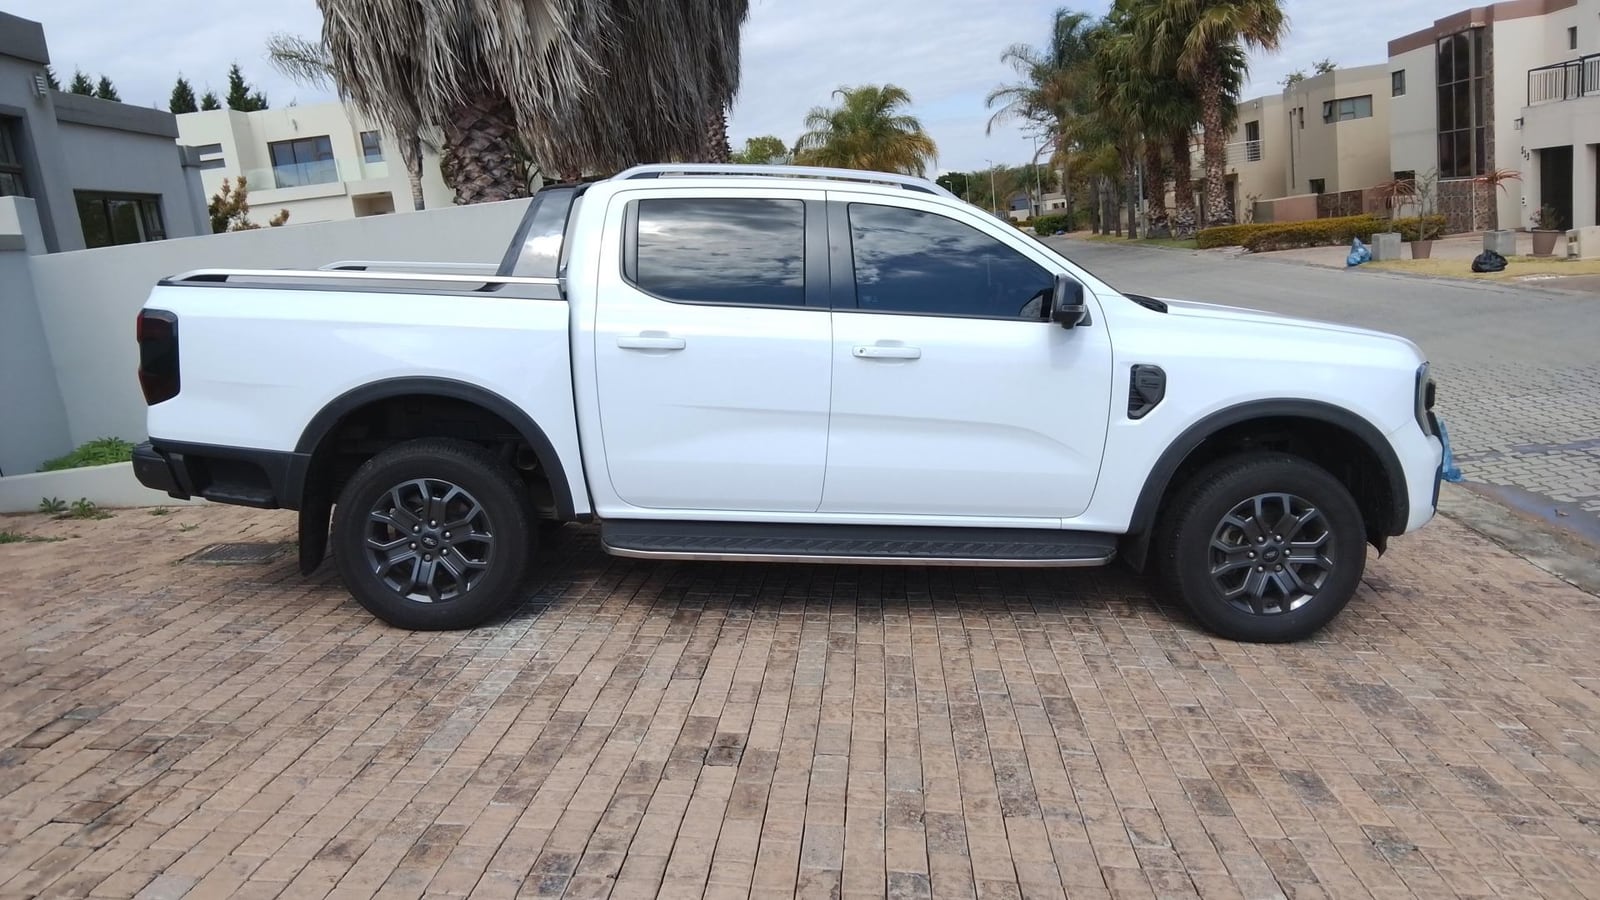
The bakkie most people mean by “a R500,000 double cab” is a 2023 Ranger XLT 2.0 4x4 automatic. It asks about R490,000 with about 90,000 km. The middle half of them ask between R450,000 and R530,000. Put down 10 percent, take 72 months, no balloon.
| Item | Amount | What you are looking at |
|---|---|---|
| Price | R490,000 | A 2023 Ranger XLT 2.0 4x4 automatic, about 90,000 km |
| Deposit | R49,000 | 10 percent |
| Amount financed | R442,200 | Price less deposit, plus the R1,207.50 initiation fee |
| Rate | 10.5 percent | Prime, 22 September 2026 |
| Term | 72 months | Six years |
| Instalment | about R8,370 | Including the R69 monthly fee |
| Total paid | about R652,000 | The deposit plus 72 instalments |
| Of which interest | about R156,000 | The cost of borrowing |
| Of which fees | about R6,200 | R1,207.50 once and R69 a month |
The bakkie costs R490,000. Owning it on this deal costs about R652,000. The R162,000 gap is interest and fees, and it is the number to hold in your head.
A common guide is that the instalment should be no more than 20 percent of your salary before tax. On this deal that means a salary of about R42,000 a month, and it covers the instalment only.
The term: 60, 72 or 96 months
Six years is now the normal term in South Africa, and MFC goes to eight. Here is the same Ranger on three terms.
| Term | Instalment | Total paid | Interest and fees | What it means |
|---|---|---|---|---|
| 60 months | about R9,570 | about R623,000 | about R133,000 | R1,200 a month more, R28,000 saved |
| 72 months | about R8,370 | about R652,000 | about R162,000 | The usual term now |
| 96 months | about R6,900 | about R711,000 | about R221,000 | R1,480 a month less, R59,000 more in all |
A year less costs R1,200 a month and saves about R28,000. Two years more saves R1,480 a month and costs about R59,000. On the 96 month deal this bakkie is 11 years old when the last debit order goes. The real risk, as the forums saw at once, is the buyer who “upgrades” to a dearer bakkie because the longer term makes the instalment fit.
Your deposit works the same way. Every R49,000 more on this deal takes about R920 off the instalment and about R17,000 off the interest.
The balloon
A balloon (banks also say residual) is a lump of the price you do not pay monthly. It sits at the end of the term, and you owe it in full on the day the debit orders stop. You pay interest on it for the whole term. Banks allow up to 35 or 40 percent of the price. WesBank has said the average deal it writes carries a 37 percent balloon.
| Deal | Instalment | Owed at the end | Total paid | What it means |
|---|---|---|---|---|
| No balloon | about R8,370 | R0 | about R652,000 | The bakkie is yours after 72 payments |
| 30 percent balloon | about R6,900 | R147,000 | about R693,000 | R1,470 a month less, R41,000 more in all |
| 35 percent balloon | about R6,650 | R171,500 | about R700,000 | R1,720 a month less, R48,000 more in all |
The 35 percent balloon cuts the instalment by R1,720 a month. Over six years that looks like R124,000 saved. It is not. You still owe R171,500 at the end, and you paid interest on it the whole time, so the deal costs about R48,000 more.
At the end you have three ways out, and the banks list all three. Pay the balloon in cash. Trade the bakkie in and let the trade-in value cover it. Or refinance it as a new loan, priced on that day at that day’s prime, on a bakkie six years older, with a new initiation fee. The bank does not have to refinance you. WesBank’s own advice is that a weak credit record can mean no refinance at all. One Eastern Cape buyer lost his Polo that way after nearly five years of instalments.
The honest test is what a six or seven year old version of each bakkie asks today.
| Bakkie in this guide | 35 percent balloon | A 2020 one asks today | A 2019 one asks today |
|---|---|---|---|
| Ranger XLT double cab (R490,000) | R171,500 | about R350,000 | about R330,000 |
| Hilux 2.8 double cab 4x4 automatic (R720,000) | R252,000 | about R580,000 | about R500,000 |
| Ranger 2.2 XL single cab (R260,000) | R91,000 | about R250,000 | about R205,000 |
On paper the asks cover every balloon. Two things eat the margin. A trade-in offer is lower than an asking price, usually by 10 to 15 percent. And your bakkie will be older than these: a 2023 bought now is nine years old when the term ends, and a 2017 Ranger XLT asks about R260,000 today.
The people who make balloons work have a car allowance or a business, and a firm plan to sell before the term ends. If you plan to keep the bakkie, a balloon is a bill in year six. Save for it from month one, because nobody at the desk will tell you to.
Example two: a used Hilux 2.8 double cab
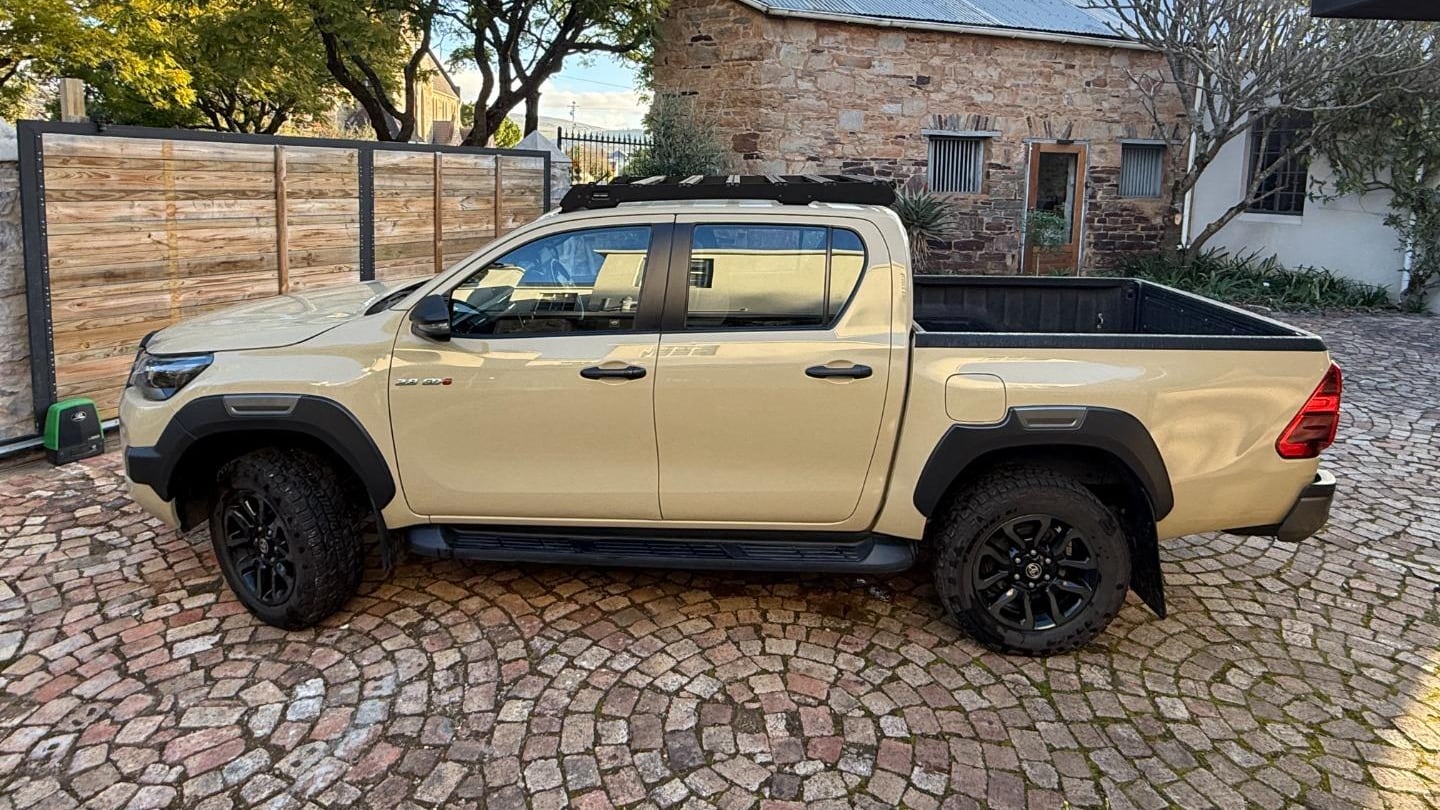
A 2022 or 2023 Hilux 2.8 double cab 4x4 automatic asks about R720,000 with about 80,000 km. The middle half ask between R630,000 and R750,000.
| Item | Amount | What you are looking at |
|---|---|---|
| Price | R720,000 | A 2022 or 2023 Hilux 2.8 double cab 4x4 automatic, about 80,000 km |
| Deposit | R72,000 | 10 percent |
| Amount financed | R649,200 | Including the initiation fee |
| Instalment | about R12,260 | 72 months at 10.5 percent, including the R69 fee |
| Total paid | about R955,000 | The deposit plus 72 instalments |
| Of which interest | about R229,000 | The cost of borrowing |
| With a 35 percent balloon | about R9,730 a month | And R252,000 owed at the end |
The Hilux costs R3,900 a month more than the Ranger on the same deal. Over the term that is about R73,000 more interest, on top of the R230,000 of extra price.
What R500,000 buys is the other way to see it. On a Ranger it buys a 2024 with about 54,000 km. On a Hilux it buys a 2021 with about 112,000 km. The Hilux gives it back at the end. A 2020 Hilux 2.8 4x4 asks about 65 percent of a new Legend’s price today. A 2020 Ranger XLT asks about 55 percent of a new XLT’s.
Example three: a single cab workhorse
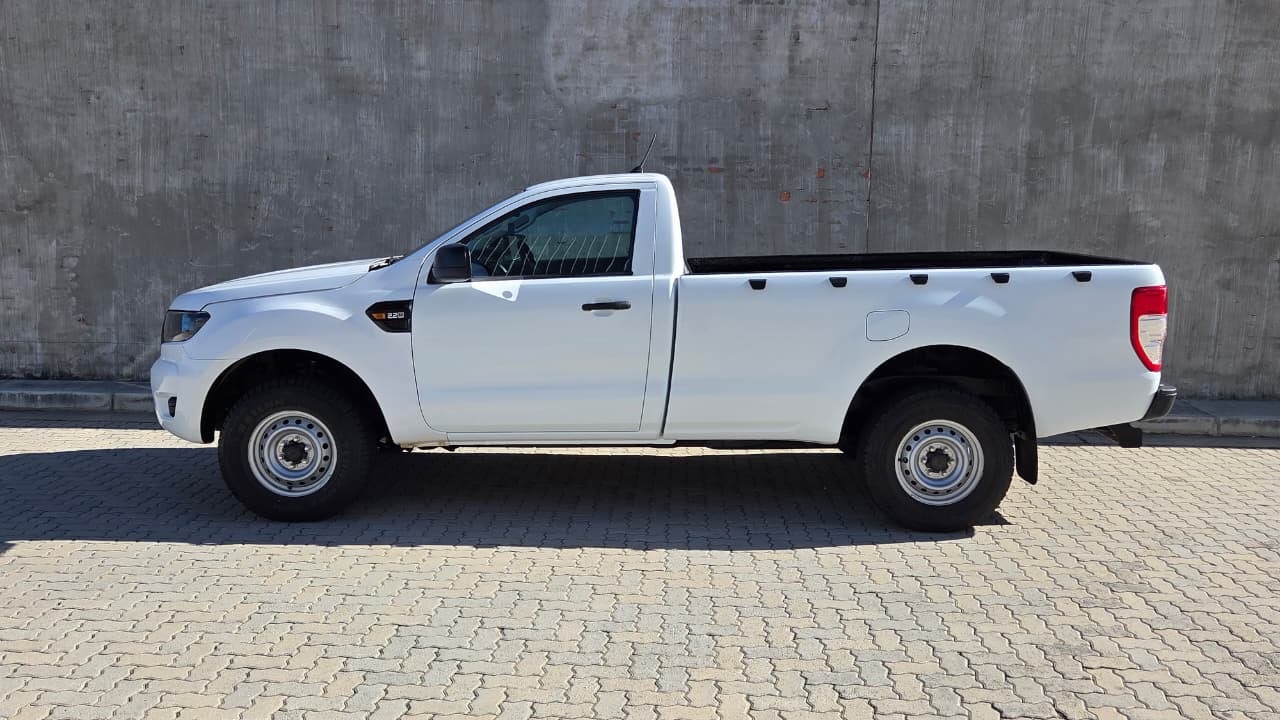
A 2020 or 2021 Ranger 2.2 XL single cab asks about R260,000, with about 150,000 km. A Hilux 2.4 single cab of the same age asks about R300,000.
| Item | Amount | What you are looking at |
|---|---|---|
| Price | R260,000 | A 2020 or 2021 Ranger 2.2 XL single cab, about 150,000 km |
| Deposit | R26,000 | 10 percent |
| Amount financed | R235,200 | Including the initiation fee |
| Instalment, 72 months | about R4,490 | Including the R69 fee; about R349,000 in all |
| Instalment, 60 months | about R5,130 | About R333,000 in all |
| Instalment, 48 months | about R6,090 | About R318,000 in all |
A bakkie this age has no service plan left, so the services come out of your pocket. And the bank’s age rules bite: MFC will not finance a bakkie older than 10 years, and the deposit it wants depends on the age. A shorter term suits it: 48 months costs about R1,600 a month more than 72 and saves about R31,000.
If you are VAT registered, the single cab’s VAT comes back and the double cab’s does not. The double cab versus single cab guide has the detail.
The rate is negotiable, and it is not fixed
Your rate is prime plus or minus a margin. The bank sets the margin on your credit record, your deposit and the bakkie’s age. MFC’s own online calculator starts at prime plus 3 percent, which is 13.5 percent today.
| Rate | Who gets it | Instalment | Interest over 72 months |
|---|---|---|---|
| 10.5 percent | Prime, today | about R8,370 | about R156,000 |
| 10.75 percent | Prime if the Reserve Bank adds a quarter point | about R8,430 | about R160,000 |
| 12.5 percent | Prime plus 2 | about R8,830 | about R189,000 |
| 13.5 percent | Prime plus 3, the default on MFC’s calculator | about R9,060 | about R205,000 |
Two points is about R460 a month and R33,000 over the term. Most vehicle finance is linked, which means your rate follows prime. One Reserve Bank hike of a quarter point adds about R56 a month, from the next month. A fixed rate costs more at signing and does not move, so ask for both quotes.
The way to get a better rate is to bring one. Ask your own bank for a pre-approved quote before you go to the dealer, then let the finance desk try to beat it. Buyers on the forums report being told prime plus 1 by the desk when their own bank had approved them at prime. The desk earns commission on the finance, and people who worked in the trade say it rises with your rate. By law the quote must show the total cost of credit, and it holds for five business days.
The finance desk extras
After the price is agreed, a second sheet appears. This is where the money is made.
On-the-road fees. Also called delivery or admin fees: number plates, a valet, a roadworthy, a “pre-delivery inspection”. Up to R4,000. One dealer charges R2,350 to licence and register a bakkie that the Western Cape charges R744 for. In September 2025 the Supreme Court of Appeal ruled that these fees may be financed, but that the buyer must be offered the choice to pay them in cash. Ask for the fee as a line item, argue it down, and pay it in cash. Financing R4,000 over 72 months costs R5,400.
Value-added products. Tyre and rim cover, scratch and dent, paint protection, an extended warranty. The National Credit Act treats these as optional, and optional means optional. Anything you add is financed at the loan rate for the full term.
Credit life. This is insurance that pays off the loan if you die, are disabled or lose your job. The bank may insist you have it. It may not insist you buy its policy: the Act says you must be told of your right to use your own. The bank must also tell you what commission it earns on its policy. The same applies to comprehensive insurance: required, but not the bank’s.
“The discount is only if you finance.” A common line on new bakkies, because the finance deal is where the dealer’s margin is. Negotiate the price on its own, and ask what the desk earns from the bank.
The costs outside the instalment
Here is the Ranger from example one, driven 2,000 km a month, with everything that arrives after the instalment.
| Item | A month | What you are looking at |
|---|---|---|
| Instalment | about R8,370 | 72 months, 10 percent deposit, 10.5 percent |
| Insurance | R1,200 to R2,300 | Comprehensive on a 2.0 Ranger or 2.8 Hilux double cab; Gauteng quotes on a Hilux run to R4,000 |
| Tracker | R85 to R220 | Most insurers want one on a Hilux or Ranger; some want two |
| Diesel | about R5,700 | 2,000 km at 9.5 litres per 100 km and R30 a litre |
| Licence disc | about R100 | R1,100 to R1,400 a year for a double cab, most in Gauteng, least in North West and the Free State |
| Servicing | R500 to R750 | Out of plan: about R4,500 for a minor service, R8,000 to R10,000 for the big one at 120,000 km |
| All in | about R16,000 to R17,500 | About double the instalment |
Diesel is the reason. Fifty ppm diesel was about R30 a litre inland at the start of September 2026, up about R10 a litre in a year, and now dearer than petrol. A Ranger 2.0 bi-turbo or a Hilux 2.8 uses 9.5 to 10 litres per 100 km in South African road tests. The engine choice barely moves the bill. The kilometres do.
On servicing, a 2023 Hilux at 80,000 km has about one dealer service left in its plan. A 2023 Ranger is only in Ford’s plan if the first owner paid for it. The 2.0 Ranger’s timing belt job costs R10,000 to R18,000 at a dealer. It falls due at around 120,000 km, so a 2023 at 90,000 km reaches it inside the term.
Insurance is the line people cancel, and WesBank has warned that most cars on South African roads are uninsured. Cancel it on a financed bakkie and a theft leaves you paying for a bakkie you no longer have. Typical premiums, from one comparison site’s averages:
| Bakkie | Average premium a month |
|---|---|
| Ranger 2.2 double cab | about R1,100 |
| Ranger 2.0 XLT double cab automatic | about R1,800 |
| Ranger 2.0 bi-turbo Wildtrak | about R2,200 |
| Ranger Raptor | about R4,100 |
| Hilux 2.4 Raider double cab | R1,600 to R1,800 |
| Hilux 2.8 Legend 4x4 double cab | R2,000 to R2,300 |
| Hilux 2.4 single cab | about R1,600 |
Two more things to know. The insurer pays the bakkie’s retail value, not what you owe; shortfall cover, sold separately, pays the gap, and it matters most with a balloon. And a canopy, bars or a roof rack are not covered unless they are listed on the policy.
Negative equity: the years you owe more than it is worth
A bakkie loses value fastest in its first two years. A loan pays off its capital slowest in its first two years. For a while you owe more than the bakkie would fetch, and if you must sell then, you write a cheque for the difference. Here is a new Ranger XLT 4x2 at R615,000 with no deposit over 72 months. The last two columns show what a Ranger XLT of that age asks today, and a trade-in offer 15 percent under that.
| Months in | Still owed | A Ranger XLT that age asks today | At a trade-in offer | Where you stand |
|---|---|---|---|---|
| 12 | about R538,000 | about R533,000 | about R453,000 | R85,000 short |
| 24 | about R452,000 | about R533,000 | about R453,000 | Even |
| 36 | about R356,000 | about R490,000 | about R417,000 | R60,000 clear |
| 48 | about R250,000 | about R382,000 | about R325,000 | R75,000 clear |
Today’s asks for older bakkies are a guide, not a forecast, and the step between year three and year four is the change of shape. The pattern still holds. With no deposit you are short in year one, level in year two and clear from year three. Add a 35 percent balloon and you are short at trade-in value for four of the six years. A deposit shortens the danger window. A balloon stretches it across the term.
The banks see the same thing. FirstRand’s 2026 results say WesBank raised its provisions because used prices are weaker than expected, with cheaper new brands pushing them down. The Chinese double cab guide covers that pressure.
Used or new: the bank’s rules
A used bakkie carries the same fees and the same rights. What changes is age. MFC’s rules are public. The vehicle may not be older than 10 years. A rebuilt or stolen-and-recovered bakkie is out. The loan must be more than R50,000. The balloon (up to 35 percent) and the deposit both depend on the bakkie’s age. Absa offers 24 to 72 months, fixed or linked, and its calculator runs to 96 months and a 40 percent balloon.
You may pay extra on any loan at any time without penalty. On a loan over R250,000 with a linked rate, settling early can cost up to three months’ interest, about R11,600 on the Ranger example. Give the bank 90 days’ written notice and that charge falls away. Under R250,000 there is no penalty at all.
When you cannot pay
The bank cannot take the bakkie on the first missed debit order. It must send you a written notice offering a plan to catch up. It can only go to court after 20 business days in arrears, and 10 business days after that notice. You can catch up at any point until the bakkie is sold. Do not let anyone “take over the payments”: the contract stays in your name. You may hand the bakkie back in writing, but the bank sells it at auction and you owe the shortfall: the balance, the balloon and the costs. The ex-fleet guide shows what those repo sales look like from the buyer’s side. If it is going wrong, sell the bakkie yourself first.
The business angle
A business can take an instalment sale, where the bakkie is yours at the end and the interest is the deduction. Or it can take a lease, where the bank owns the bakkie and the rental is the deduction. Which is better is a question for your accountant, and a tax saving is never a reason to buy a dearer bakkie. A work bakkie must also be insured for business use, or a claim can be refused.
Before you sign
- Ask for the total cost of credit, not the instalment. It is on the quote by law, and the quote holds for five business days.
- Get a pre-approved rate from your own bank first, then make the desk beat it.
- Ask whether the rate is linked or fixed, and what fixed costs.
- Ask for the on-the-road fee as a line item, argue it down, and pay it in cash.
- Decline the extras, or take the list home and price them yourself.
- Use your own credit life and comprehensive cover if you have it, and ask what commission the bank earns on theirs.
- Decide the balloon on what a six year old one asks today, less 15 percent, not on the instalment.
- Get the insurance quote and a shortfall cover quote before you sign, and list the canopy and bars on the policy.
- Add diesel, insurance, the tracker and servicing before you decide it fits.
- Check the price against the going rate for its year on the listings, where every bakkie has a finance calculator. There is no point financing R30,000 of overpricing for six years.
Questions people ask
What is the monthly instalment on a R500,000 bakkie?
At the September 2026 prime rate of 10.5 percent, a R490,000 Ranger double cab with a 10 percent deposit costs about R8,370 a month over 72 months, including the R69 bank fee. That adds up to about R652,000 over the six years, of which about R162,000 is interest and fees. With no deposit the instalment is about R9,290. Every R49,000 of deposit takes about R920 off the instalment and about R17,000 off the interest. The rate moves with prime, so ask for a fresh quote.
Is a balloon payment on a bakkie a bad idea?
A balloon is part of the price you do not pay monthly. You owe it in full when the term ends, and you pay interest on it the whole time. On a R490,000 bakkie a 35 percent balloon cuts the instalment by about R1,720 a month but adds about R48,000 to the total, and leaves R171,500 owing in year six. It works if you will sell or trade the bakkie before then and its value covers the balloon. A trade-in offer is lower than an asking price, so test it against 85 percent of what a six year old one asks today. If you plan to keep the bakkie, save for the balloon from month one.
What interest rate will I pay on vehicle finance?
Prime is 10.5 percent as of 22 September 2026. A strong credit record with a deposit gets about prime. One bank's own calculator starts at prime plus 3 percent, which is 13.5 percent, and the law caps vehicle finance at about 24 percent. On a R490,000 bakkie over 72 months, two points on the rate is about R460 a month and about R33,000 over the term. Get a quote from your own bank first and make the dealer beat it. A linked rate moves the month after every Reserve Bank decision.
How much does a bakkie cost a month all in?
About double the instalment. A R490,000 Ranger double cab on finance is about R8,370 a month. Add comprehensive insurance at R1,200 to R2,300, a tracker at about R100 to R200, diesel at about R5,700 for 2,000 km a month at R30 a litre, the licence at about R100 a month and servicing at R500 to R750, and the bakkie is about R16,000 to R17,500 a month. Diesel is now the second biggest line, and it is more than half the instalment.
Figures are seller asking prices aggregated from South African listing platforms and dealers, not final selling prices. Most vehicles transact below asking. Updated continuously.
financemoneybuying-guide